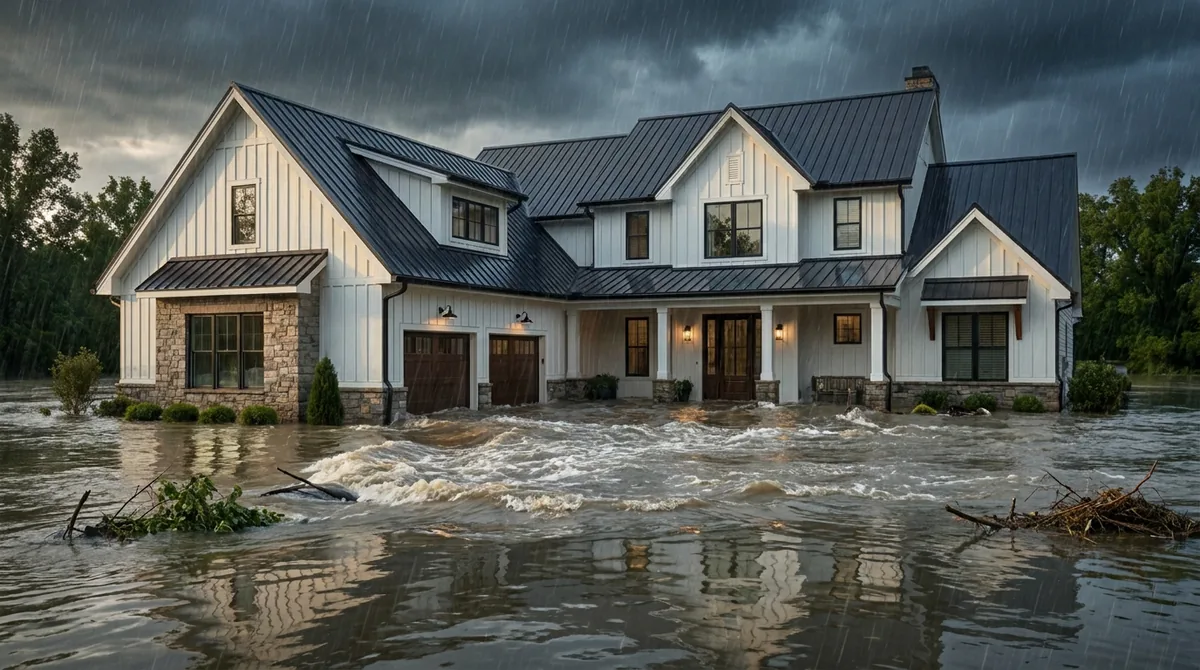
Floodwater rising near a North Texas home
Home / Flood Insurance

Arlington Flood Insurance: The policy your home insurance leaves out.

Your homeowners policy will not pay a flood claim. Not one dollar. We write NFIP flood coverage for Arlington and DFW homes, where flash flooding hits creeks, streets, and low-water crossings fast.

$0
Flood Coverage In A Home Policy
$250k
NFIP Building Limit
30 Days
NFIP Waiting Period
15 min
To a Real Quote
The Quick Answer

Standard homeowners insurance excludes flood. Rising water, flash flooding, and creek overflow require a separate flood policy, written through the National Flood Insurance Program (NFIP). NFIP limits are $250,000 for the building and $100,000 for contents, with a 30-day waiting period unless the policy is bought in connection with a loan closing. Flood insurance is only mandatory in high-risk A zones with a federally backed mortgage, but in Arlington, heavy storms can push Johnson, Rush, Village, and Fish creeks and the Trinity River system out of their banks and flood streets and low-water crossings fast, including in lower-risk zone X neighborhoods. Pricing is property-specific under Risk Rating 2.0. A car caught in floodwater is a comprehensive claim on your auto policy, not a flood claim. Robinson Legacy Partners, the Allstate agency of Clarence Robinson II in Arlington, quotes NFIP flood coverage for free, in seven languages, at (817) 262-5300.

Home policy pays
$0 for flood, always
NFIP limits
$250k building / $100k contents
Waiting period
30 days (none at loan closing)
Free quotes
(817) 262-5300
Arlington Flood Insurance, The Short Version

The most important policy most DFW homes don't have. Yet.

Here is the sentence that surprises almost everyone, so we will put it first: your homeowners policy pays nothing for flood damage. Not a reduced amount. Nothing. Rising water, flash flooding, and overflow from creeks, rivers, and overwhelmed storm drains are excluded from standard home policies in Texas, and the exclusion does not care how long you have been a customer. Flood coverage is its own policy, written through the federal National Flood Insurance Program (NFIP), and North Texas needs it more often than people think.

The second surprise is how DFW floods. It is not a slow tide; it is flash flooding. A slow-moving spring or fall thunderstorm can drop heavy rain on hard clay soil and acres of pavement faster than creeks and drainage can carry it away. Johnson Creek, Rush Creek, Village Creek, and Fish Creek all wind through Arlington neighborhoods, the Trinity River system drains the whole Metroplex, and streets and low-water crossings can go from dry to dangerous in minutes. Lenders only require flood insurance in high-risk zones, but the mandate map and the risk map are two different maps.

The third thing to know is how pricing works now. FEMA prices every property individually under Risk Rating 2.0, looking at elevation, distance to water, foundation type, and rebuild cost, so your neighbor's premium tells you very little about yours. And a new NFIP policy generally carries a 30-day waiting period, which means the time to buy is before spring storm season, not when the radar turns red.

That is the entire offer here. We will pull your flood zone, quote your NFIP coverage, size the building and contents limits to your actual house, and show you how the flood policy fits next to your home policy. A flooded car, by the way, is an auto policy matter, one more reason the whole plan belongs with one local agent. Call (817) 262-5300 and we will do it in about 15 minutes, in any of our seven languages.
What a flood policy covers. And the three things it never does.

A flood policy is simpler than a homeowners policy — two main coverages plus a code-upgrade helper — but its limits, definitions, and gaps are exactly where claims go sideways. Here is the map.

Building
Up to $250k NFIP

Building Property

The structure itself: foundation, walls, electrical and plumbing systems, furnace and water heater, built-in appliances, and attached fixtures. The NFIP caps this at $250,000. If your home would cost more to rebuild, ask us what's available above the NFIP limit.

Contents
Up to $100k NFIP

Personal Property

Furniture, clothing, electronics, and the rest of what you own, on its own limit and deductible. The catch: the NFIP pays contents at actual cash value — depreciated worth, not replacement price. Keep that gap in mind when you choose the limit.

ICC
Up to $30k

Increased Cost of Compliance

If a flood leaves your home substantially damaged, the city can require you to rebuild to current floodplain code — elevated, floodproofed, or relocated. ICC adds up to $30,000 toward exactly those costs, and for homes along Arlington's creeks it is the coverage nobody knows they have.

Definition
Read this one

What Counts as a Flood

The NFIP definition: surface water covering two or more acres of normally dry land, or two or more properties, at least one of them yours. Rising water from a creek, the river, or overwhelmed street drainage qualifies. A pipe bursting inside the house does not — that claim belongs to your home policy.

Deductibles
Two of them

Building & Contents Deductibles

A flood policy carries separate deductibles for building and contents, chosen when you buy. Raising them lowers the premium; just pick numbers your savings can actually absorb the week after a storm, when everything else is also due.

Above the cap
Over $250k

Higher-Value Homes

Plenty of DFW homes would cost more than $250,000 to rebuild, and the NFIP building limit stops there. If yours rebuilds for more, ask us what's available above the NFIP limit before a serious flood tests the gap.

Not covered
Living costs

Temporary Housing (NFIP)

The NFIP pays nothing toward rent or hotels while your home is unlivable, a gap that surprises families at the worst time. Plan for it with emergency savings, and know that homeowners loss-of-use coverage generally does not respond to a flood either.

Not covered
Vehicles

Cars & Trucks

A flooded vehicle is not a flood-policy claim. It is covered by the comprehensive coverage on your auto policy — if you carry it. With low-water crossings and underpasses across DFW that flood in heavy storms, dropping comprehensive to save a few dollars is a bet against the weather.

Not covered
Outside

Land, Pools & Landscaping

Flood insurance rebuilds the house, not the yard. Land, fences, pools, decks, septic systems beyond limited coverage, and landscaping are excluded, along with most finished space and belongings below the lowest elevated floor.

Do you actually know your flood zone?

Most homeowners are guessing. We will pull your zone, check your address against the nearby creeks, and quote your NFIP coverage in about 15 minutes.

Coverage Basics

The four decisions that actually shape your flood policy.

Flood insurance looks simple until you read the policy. These are the choices that decide what a claim actually pays.

1. The NFIP, through your local agent

The National Flood Insurance Program is the federal flood program: standardized coverage, federally backed, with set limits and one enormous virtue — it generally does not refuse to renew you for filing claims. You do not have to figure it out alone; NFIP policies are sold through insurance agents, and we write flood coverage for our clients right here through the agency.

That matters because flood rarely happens in isolation. The same storm that fills a creek can take a roof, flood a car, and put a family in a hotel. Having your home, auto, and flood coverage with one local agent means one person who knows the whole plan, and one number to call: (817) 262-5300.

2. The building limit, and the cap above it

Your building limit should track what it costs to rebuild the house, the same rebuild-cost logic as your homeowners dwelling limit. The NFIP stops at $250,000, and many homes across Arlington, Mansfield, and the rest of DFW rebuild for more than that. If yours does, ask us what's available above the NFIP limit.

3. Contents, the coverage everyone skips

Building and contents are separate elections, and skipping contents to save money is the most common flood-policy regret. Watch the settlement basis: the NFIP pays contents at depreciated actual cash value, not replacement cost. On a house full of furniture, appliances, and electronics after two feet of water, that difference is not academic.

Renters are not exempt from any of this — a landlord's flood policy covers the building, never your belongings. A contents-only flood policy is often inexpensive and exists for exactly this.

4. Your rate, your elevation, and the glide path

Under Risk Rating 2.0, your NFIP price keys off elevation, distance to flooding sources, foundation type, and rebuild cost. An elevation certificate is optional now, but providing one can only be used to lower your rate, never raise it — on an elevated or favorably graded lot it is worth the survey.

Annual increases on an existing policy are capped, which creates a glide path: the longer a policy has been in force, the further below full-risk price it may sit. That trajectory can be assumed by a buyer at closing, which makes "can I take over the seller's flood policy?" one of the smartest questions in a DFW home purchase.

Already have a flood policy? Send it over.

Building limit, contents, deductibles, and whether the limits still fit the house you live in today. We will flag what is exposed and what is fine. No pressure either way.

The DFW Flood Map, Honestly

Zones, creeks, and what the Arlington map does not tell you.

You have seen the maps and heard the letters. Here is what they actually mean for your address.

How the zones work

FEMA maps sort property into zones. A and AE zones are high-risk Special Flood Hazard Areas with at least a 1 percent annual flood chance — the "100-year" floodplain, which over a 30-year mortgage works out to roughly a 1-in-4 chance of flooding. If your home sits in a high-risk A zone and carries a federally backed mortgage, your lender must require flood insurance. Shaded X is moderate risk, unshaded X is lower risk, and neither carries a mandate.

In Arlington the zones follow the water: Johnson Creek, which runs past the Entertainment District, along with Rush Creek, Village Creek, and Fish Creek, all part of the Trinity River watershed. Two streets in the same neighborhood can land in different zones, which is why we pull the actual map panel for your address instead of guessing from the subdivision.

The map is not the risk

The mandate map and the risk map are different maps, and the gap between them is where North Texas families get hurt. FEMA has long pointed out that many flood claims come from outside high-risk zones. In DFW that looks like a zone X home where the storm drains back up during a cloudburst, a street that turns into a channel in minutes, or a house below a creek that never left its banks until the night it did.

Federal disaster assistance is not a plan, either. It requires a presidential declaration, much of it arrives as loans that must be repaid, and grants are typically a small fraction of real repair costs. The zone X address that skips coverage is often skipping some of the least expensive flood insurance available while running the largest uncovered risk in the household. We would rather quote it and let you decide with the number in front of you.

Risk Rating 2.0, map changes, and the 30-day clock

Since 2021 the NFIP prices every property individually — elevation, distance to water, foundation, rebuild cost — under Risk Rating 2.0. Zones still control the lender mandate, but not your price. Increases on an existing policy are capped year to year, so a policy bought early rides a glide path below full-risk pricing, and that glide path can transfer to a buyer who assumes the policy.

Flood maps also change. FEMA and local communities revise them as new studies are completed and development reshapes how water moves, and a revision can move a property into a high-risk zone and trigger the lender mandate. Coverage already in force when a map changes is generally better positioned than coverage started afterward. And because a new NFIP policy usually waits 30 days to take effect, the smart moment to buy is before the spring storms, not the afternoon the flash flood watch is issued.

Near Johnson, Rush, Village, or Fish Creek?

Spring storms do not wait 30 days, and neither should your flood coverage. Let us pull your zone and quote NFIP coverage, no charge and no pitch.

Seven honest ways to lower your flood premium. Without hollowing out the policy.

In flood insurance the two biggest levers are timing and getting the rating details right, because Risk Rating 2.0 made every property its own price. The rest stack on top.

1

Buy before storm season, and before any map change

A new NFIP policy generally waits 30 days to take effect, and coverage already in force when a flood map changes is generally better positioned than coverage bought after. Buying early also starts the glide path sooner. This is the rare insurance decision where the calendar is doing half the work.

2

Make sure your home is rated correctly

Under Risk Rating 2.0, details like foundation type, number of floors, and where the furnace and water heater sit all feed the price. We confirm the building details on your policy so you are not paying for a house you do not have. Taking whichever renewal shows up unexamined is how flood premiums quietly bloat.

3

Ask about assuming the seller's policy

Buying a home that already carries NFIP coverage? The policy can be assumed at closing, glide-path discounts and all, which is often meaningfully cheaper than starting fresh at today's full-risk price. Ask before you close; it cannot be reconstructed after.

4

Get an elevation certificate if the lot favors you

Optional under Risk Rating 2.0, and one-directional: FEMA will use it to lower your rate, never to raise it. On an elevated slab, a favorably graded lot, or a home above the base flood elevation, the survey can pay for itself.

5

Raise the deductibles your savings can cover

Building and contents deductibles are separate elections, and raising them trims the premium. Pick numbers you could actually write checks for the week after a storm, when the fence, the car, and the wind/hail deductible may all be due at once.

6

Claim the mitigation credits

Proper flood vents in enclosures, machinery and utilities elevated above the first floor, and filled-in below-grade spaces all move the Risk Rating 2.0 price. If you are already renovating, an hour of planning can earn a lower rate for years.

7

Never let it lapse

Continuous coverage protects your glide path and any statutory discounts; a lapse can reset you to full-risk pricing — and re-entry means waiting 30 days you may not have in storm season. Autopay the flood policy and forget it. This is the one policy where loyalty to the coverage itself pays.

Every flood situation is a different problem. We quote them all.

A creek out back, a closing date, a rental, a house above the NFIP cap. Each changes how the flood policy should be built.

Under contract, or storm season approaching?

Tell us the address and we will pull the zone, quote your NFIP coverage, and tell you what would make it cheaper. Straight answer, no obligation.

Flood insurance in Arlington. And every creek across DFW.

Flood pricing is property by property, and two streets in the same subdivision can sit in different zones. Local knowledge is not a slogan when the creek is behind your fence.

Arlington flood insurance questions. Straight answers.

Doesn't my homeowners insurance cover flooding?

No. Standard homeowners policies exclude flood: rising surface water, flash flooding, and overflow from creeks, rivers, and drainage. The exclusion applies no matter how long you have had the policy.

The dividing line is where the water came from. A pipe bursting inside the house is sudden internal water damage and belongs to your home policy. Water coming in from outside and rising belongs to a flood policy — and only a flood policy.

Am I required to buy flood insurance?

Only if your home sits in a FEMA high-risk zone, such as the A and AE zones along DFW's creeks and rivers, and carries a federally backed mortgage. Then the lender must require it, and will.

Outside those zones it is optional, which is precisely the trap: flash flooding in North Texas does not stay inside the lines, and many flood claims come from outside high-risk zones. The mandate map and the risk map are two different maps. We quote it either way and let you decide with the number in front of you.

How much does flood insurance cost in Arlington?

It depends on the property, literally. Under Risk Rating 2.0, FEMA prices each address on elevation, distance to water, foundation type, and rebuild cost, so a home backing onto a creek and one on higher ground a mile away can see very different prices.

Lower-risk zone X homes are often among the least expensive to insure, which is exactly why they are worth quoting. We pull the real number for your address in about 15 minutes.

What does an NFIP flood policy cover?

Up to $250,000 for the building — structure, systems, built-in appliances — and up to $100,000 for contents, each with its own deductible. It also includes up to $30,000 of Increased Cost of Compliance toward rebuilding to current floodplain code after substantial damage.

Know the two catches: contents pay at depreciated actual cash value, and the NFIP pays nothing toward temporary housing while your home is unlivable. Plan your limits and your emergency savings around both.

Can I get more than $250,000 of flood coverage?

The NFIP building limit is $250,000 and the contents limit is $100,000. Those limits fit a lot of homes, but not every one: if your house would cost more than $250,000 to rebuild, the NFIP alone stops short.

Ask us about options for higher-value homes. We will tell you plainly what is available for your address and how it would fit with your NFIP policy, before you need it.

Is there a waiting period for flood insurance?

NFIP policies generally take effect 30 days after purchase. The important exception: coverage bought in connection with making, increasing, extending, or renewing a home loan is effective at closing, no wait.

That 30-day clock is why the time to buy is before spring storm season, not when a flash flood watch is issued. Once the water is rising, it is too late for this storm.

I'm not in a flood zone. Do I still need flood insurance?

Everyone is in a flood zone; the question is which one, and zone X means lower risk, not no risk. In DFW, intense rain on clay soil and pavement can flood streets and homes well outside the mapped floodplain.

Here is the useful irony: lower-risk zones generally get the lowest pricing. The addresses where people skip flood coverage are often the addresses where it costs the least to carry. Get the quote before deciding it is not worth it.

What is Risk Rating 2.0?

FEMA's pricing methodology, in use since 2021. Instead of pricing by flood zone alone, it rates each property individually: elevation, distance to flooding sources, foundation type, and rebuild cost. Zones still control the lender mandate, but not your NFIP price.

Increases on an existing policy are capped year to year, creating a glide path below full-risk pricing for long-held policies — and that glide path can transfer to a buyer who assumes the policy at closing. Both are reasons the smart move is usually to get covered early and stay covered.

Will FEMA disaster assistance cover me if I skip flood insurance?

Not meaningfully. Federal assistance requires a presidential disaster declaration, much of it arrives as SBA loans that must be repaid, and typical individual grants are a small fraction of real repair costs.

Assistance is a safety net for the uninsured, not a substitute for coverage, and most flood events never trigger a declaration at all. A flash flood that swamps a few Arlington streets may never make the national news, but it still ruins the floors.

Does flood insurance cover my car or temporary housing?

No on both, under the NFIP. A flooded vehicle is a comprehensive claim on your auto policy. With low-water crossings and underpasses across DFW that flood in heavy storms, think twice before dropping comprehensive, and never drive into moving water: turn around, don't drown.

The NFIP pays nothing toward rent or hotels while your home is unlivable. Build that into your emergency plan, and let us review your home and auto coverage alongside the flood policy so there are no surprises.

Can a flood policy transfer when a home is sold?

Yes. An NFIP policy can be assumed by the buyer at closing, and the seller's capped-increase glide path transfers with it. On a home that has carried flood coverage for years, assuming the existing policy can beat starting a new one at today's full-risk price.

It has to be arranged before closing, not reconstructed after. If you are buying anywhere near a DFW creek, put "can I assume the flood policy?" on the checklist next to the survey.

Can my flood zone change?

Yes. FEMA flood maps are revised as new studies are completed and as development changes how water moves through a watershed. A revision can move a property into a high-risk zone, which triggers the mandatory-purchase rule for federally backed mortgages, or out of one.

Coverage already in force when a map changes is generally better positioned than coverage bought after, and continuous coverage protects your glide path. We check your zone when we quote and can look again at renewal.

Still have questions? Call (817) 262-5300. We will give you a straight answer.

Find out what your flood risk really costs to cover.
Free, fast, and in plain English.

Tell us the address. We will pull the zone, quote your NFIP flood coverage, and hand you the number in about 15 minutes.