Two policies you already own. Neither one covers the toys.
Here is the assumption that costs Texas owners the most: "the truck's insured and the house is insured, so the stuff they tow and store must be too." Your auto policy lends its liability to a trailer only while it is hitched, and never covers the trailer's own damage. Your homeowners policy extends a little coverage to small, low-powered craft, and stops entirely at anything with a real motor — especially once it leaves the driveway or floats a liability claim on open water.
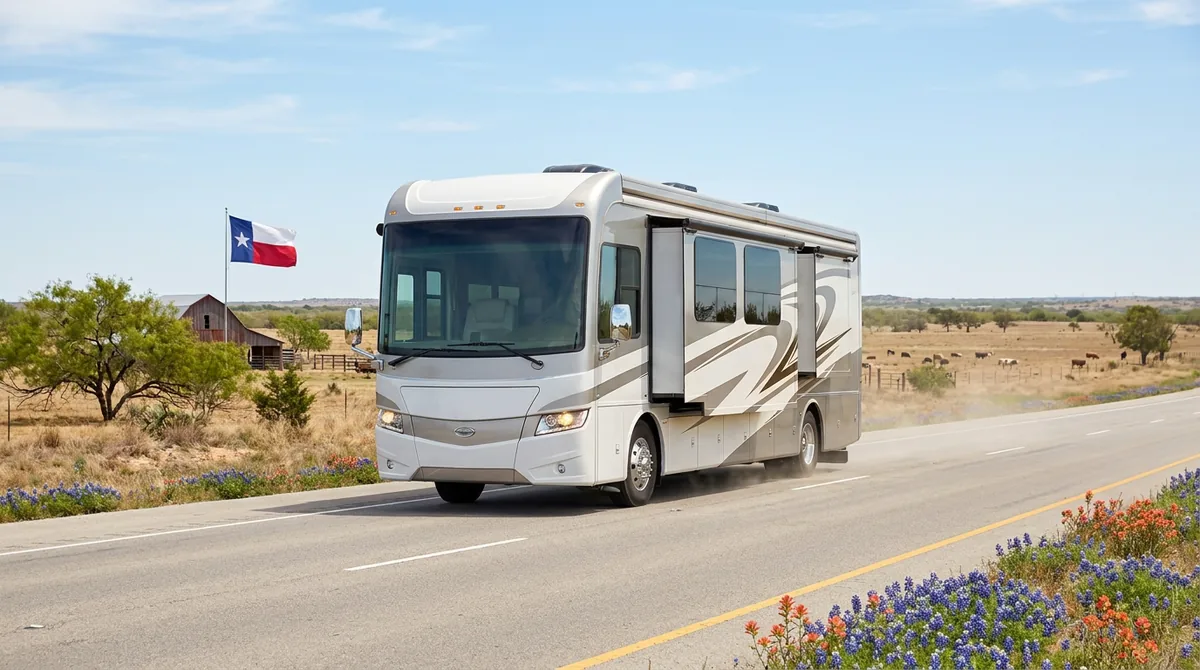
So the toys get their own coverage, matched to what they are. A motorhome is a vehicle and a house at once: 30/60/25 liability because Texas registers it like a car, physical damage because a Class A is a rolling six-figure asset, and vacation liability for the half of its life it spends parked with you living in it. A travel trailer needs its own physical damage policy for the hail, the blowover, and the storage-lot theft. A boat on Joe Pool Lake or Lake Arlington answers to the marina and the lender more than the state, and the smart package includes fuel spill and wreck removal, because a sunk boat creates bills that float. An ATV or side-by-side needs its own policy the moment it rolls off your property.
Two Texas notes. Texas is one of the most popular full-timer domicile states in the country. If the rig is your residence, ask us about full-timer coverage options, because running a recreational policy on a full-time rig is a claim dispute on layaway. And North Texas weather works every shift: hail and straight-line wind in the spring, flash flooding along the creeks, and a hard freeze most winters. That is why comprehensive on a stored rig or boat is the coverage that quietly earns its premium all year.
Tell us what is in the driveway and what is in the slip. One call, one local Allstate agent, the whole fleet — and bundling can lower what you pay versus keeping separate policies.